With everything that has been going on lately, have you found yourself wondering (or trying not to) what the best way is to save for a child’s future? I know we have!
Today I want to talk about something I am passionate about… setting up a savings fund for our children’s financial security. Not only are you setting your child up for success in the future, but it’s also a great way to teach them financial literacy at an early age.
If you’ve been considering looking for an opportunity to start investing in your child’s future, researching these topics is the crucial first step. And if your family is also trying to pay off debt while still getting away for a real vacation, you don’t have to pick one.
That’s the exact balance we walk through in our guide on how to build a family travel fund, which pairs well with everything below.
Best Way To Save For A Child’s Future: A Beginner’s Guide To Financial Planning For Your Kids
In this post, we are going to be taking a look at three well-established investment options for your child: a Custodial IRA, a UTMA/UGMA, or a 529 College Savings plan. I am going to break down your long-term investment plan options and help you clarify the best way to save for a child’s future.
You may have heard of at least one, if not all, of these college savings options. But any of these investment opportunities can become the cornerstone of your plan to save for a child’s future, and can help you decide how much you should save for a child.
While reading through this article, keep in mind that you can utilize any of these as a stand-alone or even a combination of financial instruments. They are designed to help beginners create long-term investment plans for their children.
What Is The Best Way To Save For A Child’s Future?
- Open a custodial Roth IRA once they earn income
- Start a 529 plan as early as possible
- Use a UTMA or UGMA for flexible gifted assets
- Automate small monthly contributions instead of lump sums
- Combine accounts based on your family’s specific goals
Best Investment Plans to Save for a Child’s Future
So let’s dive into these financial instruments and touch on the basics for the Custodial IRA, the UTMA/UGMA, and the 529 College Savings plan, because the right combination is really what determines how well you save for a child’s future.
What is a Custodial IRA?
A custodial IRA of any type is simply money saved into an Individual Retirement Account from income earned by your child. As the term “individual” implies, there are no co-owners of retirement accounts, so it is owned by your child. But governed by you or an assigned adult custodian.
I’m going to touch on the two most common IRAS’s that you can open for your child as a custodial account, the traditional and the Roth.
What is a Traditional IRA?
The Traditional Individual Retirement Account (IRA) was established in 1974 as a long-term savings and investment vehicle for retirement, touted as a “personal pension plan,” with various tax advantages as an inducement.
A traditional IRA allows you to make pre-tax contributions and the investments in the account grow tax-deferred. In retirement, the owner (in this case your child) will then pay income tax on withdrawals.
What is a ROTH IRA?
The ROTH IRA specifically is another version of the Individual Retirement Account that was established in 1997 and named after a Delaware senator, William Roth.
The Roth IRA is very similar to a Traditional IRA, with the most noticeable difference when it comes to taxes and being taxed!
The Roth allows you to contribute after-tax money in the investment account and therefore is not tax-deductible. The upside is, no matter how prosperous the account becomes, once you start withdrawing funds at retirement, the money is tax-free!
What’s the biggest difference between Roth IRA vs Traditional IRA?
Taxes, taxes, and “less” taxes!? Here’s where it can get tricky, based on your child’s potential to earn as well as how much income you think he/she will have in retirement. However, I want to keep this post on the “lighter” side or at a beginner level. So let’s stick to a few key differences with a quick recap of the info above:
- With a Roth IRA, you pay taxes on your income before you contribute to your account and then enjoy tax-free withdrawals later.
- With a traditional IR, you enjoy your tax advantage by taking deductions now and paying taxes on the withdrawals later.
(Prepare for an exciting caveat at the end of this paragraph)
You can think of it like this: If you choose to set up a Roth, it will function more like a regular investment account with fewer restrictions than the Traditional IRA, with some tax benefits.
On the flip side, the Traditional IRA is set up to function more like a personal pension plan. You will receive considerable tax breaks with the Traditional IRA. But you will also deal with greater restrictions and rules for accessing the funds and when you have to take distributions.
Here’s the caveat: While that information is correct for a Roth IRA vs. a Traditional IRA, we are talking about investing earned income on your child’s behalf. If your little one is talented or entrepreneurial and making an income, the implications of long-term savings and compounded interest are phenomenal! This can’t be stressed enough; the money in your child’s Custodial Roth IRA grows TAX-FREE for decades!
How do I open a Custodial Roth IRA for my children?
Opening a Custodial Roth IRA for your child is relatively easy. To qualify, they must have earned income, just like an adult. A parent or guardian will open the account in the child’s name. They will require the child’s Social Security number as well as other basic information.
Check with your financial institution to see if they offer online services. I know Fidelity offers great information as well as a way to sign up online. The process is clear and easy to follow. If you’d like to check it out, here’s the link: https://www.fidelity.com/retirement-ira/roth-ira-kids
At What Age Can You Open A Custodial Roth IRA?
As long as your little one is earning an income, there is no lower age limit. Think of all those apple-cheeked babies and toddlers frolicking around on your TV screen… Those children get paid!
How much money can my child put in a Roth IRA in 2026?
The current amount you can contribute to an IRA (of either or both types combined) is $7,500 max per year, or up to the amount of your child’s total earned income, whichever is the lesser amount. This is the updated 2026 limit, up from the $6,000 cap that applied back in 2021, so if you last checked a few years ago, it’s worth re-running the math.
If your child earns $3,500 in a year, that is the maximum amount allowable by law you can contribute to an IRA on your child’s behalf that year. If they’re industrious enough to earn more than $7,500, the contribution amount still cannot exceed $7,500, since that’s the current combined Roth and Traditional IRA contribution limit for 2026.
*There are current income thresholds per individual that will rule out the use of a ROTH IRA. If your child is making that amount of money, you will most likely need to consult a financial advisor.
What is a 529 savings plan?
A 529 plan, also called the 529 College Savings Plan, was originally established in 1986 as a prepaid tuition plan by the Michigan Education Trust (MET). In 1996, the Internal Revenue Code added Section 529 to authorize tax-free status for qualified tuition programs. These plans allow earnings to grow tax-deferred, and if used according to plan rules for education expenses, the funds come out federal income tax-free.
Are 529 plans worth it?
The best part about a 529 plan is that while your money is growing in the account, there aren’t any taxes due on the earnings, and the rules keep getting more flexible.
Not only can the money be used for college expenses at accredited schools, but as of January 1, 2026, families can use up to $20,000 per year, per student, on K-12 tuition and related expenses at private, public, or religious schools, double the old $10,000 cap. That expanded K-12 allowance now covers a broader list of costs too, including curriculum materials, tutoring, and certain testing fees, which matters a lot if your family homeschools.
One newer option worth knowing about: under SECURE 2.0, families can now roll unused 529 funds into a Roth IRA for the same beneficiary, up to a $35,000 lifetime limit, as long as the 529 account has been open for more than 15 years and the rollover stays within that year’s IRA contribution limit. It’s a meaningful safety net if your child ends up needing less for school than you saved.
Another advantage, depending on your point of view, is that unlike a custodial account where your child is the actual owner and can do as they please with the funds at adulthood, the account owner keeps ownership of a 529 until the money is withdrawn for the named beneficiary. As long as you withdraw for qualified education expenses, that money stays free from federal income tax.
**It’s worth noting that your child, as the named beneficiary, has no legal rights to the funds in a 529 account, so with few exceptions, you can be confident the money gets used at your discretion for its intended purpose.
Who can open a 529 plan?
Anyone can open and fund a 529 savings plan. Whether you are a parent, grandparent, relative, or, surprisingly, even a friend can open a 529 savings plan and name a child as a beneficiary. Also to note, a student at 18 years of age is eligible to open and name his/herself as a beneficiary to take advantage of a 529 Savings Plan.
Custodial IRA vs 529
So as we’ve established, both of these accounts are designed to invest in your child’s future but have a few key differences. Both accounts are considered gifts, and therefore subject to gift taxation. A 529 has tax benefits when used for your child’s educational purposes. Most 529 accounts are run by state governments or school agencies. So there are more limitations on this kind of account than a custodial IRA. Custodial IRAs are typically run by private institutions or brokerage firms. And because they are not intended for education, they do not hold the same tax exemptions as a 529 and are subject to income taxes.
One more advantage I’d like to highlight, and then I’ll move on, is that these 529 plans have no annual contribution limits, age, or income limits, unlike the Individual Retirement Accounts (Roth or Traditional) that we touched on above.
Now it’s time to circle back to an older, although somewhat less talked about, version of a custodial account, the UGMA, and its newer counterpart, the UTMA. These two custodial accounts, which can also be considered trusts as the deposits to these accounts are irrevocable, are getting almost as much air time recently as the Custodial IRA’s we discussed at the beginning.
What is a UGMA or UTMA account?
The Uniform Gift to Minors Act, or UG, was first established in 1956. And revised in 1966 as a custodial account that is typically controlled by a parent or guardian. The account will then transfer ownership to the minor/named beneficiary when he/she reaches the age of majority in their state, usually 21. But in some cases, it can be as early as 18 years of age and as late as 25 years old.
When you look into one of these custodial accounts for minors,nors you’ll need to check the rules that apply to you, as it varies by state.
What is the difference between a UTMA and UGMA account?
The main difference is what assets are allowed in the accounts.
A UGMA account has cash and other financial instruments managed by the custodian until the child assumes control of the account when he/she comes of age.
The UTMA allows a minor to receive gifts of real estate, inheritances, and other property like patents or fine art without the aid of a guardian or trustee. Remember, as a donor, you can be named custodian to manage and invest the property on behalf of your child until they come of legal age.
What is the main advantage of a UGMA/UTMA account?
You’ll most likely find that there are two main advantages when it comes to using a UGMA or UTMA custodial account. First, these accounts make it easy for you to give financial gifts or assets to a child. Secondly, it follows that it avoids the need to incur expensive attorney fees to set up a special trust.
Another benefit worth noting: there aren’t any taxes on withdrawals, since all contributions are after-tax assets. But keep the current kiddie tax rules in mind. For 2026, the first $1,350 of a child’s unearned income is tax-free, the next $1,350 is taxed at the child’s own rate, and anything above $2,700 total gets taxed at the parents’ marginal rate. That’s an update from the flat $2,100 threshold that applied under the old 2017 rules, so it’s worth re-checking if your custodial account has been generating steady dividends or interest.
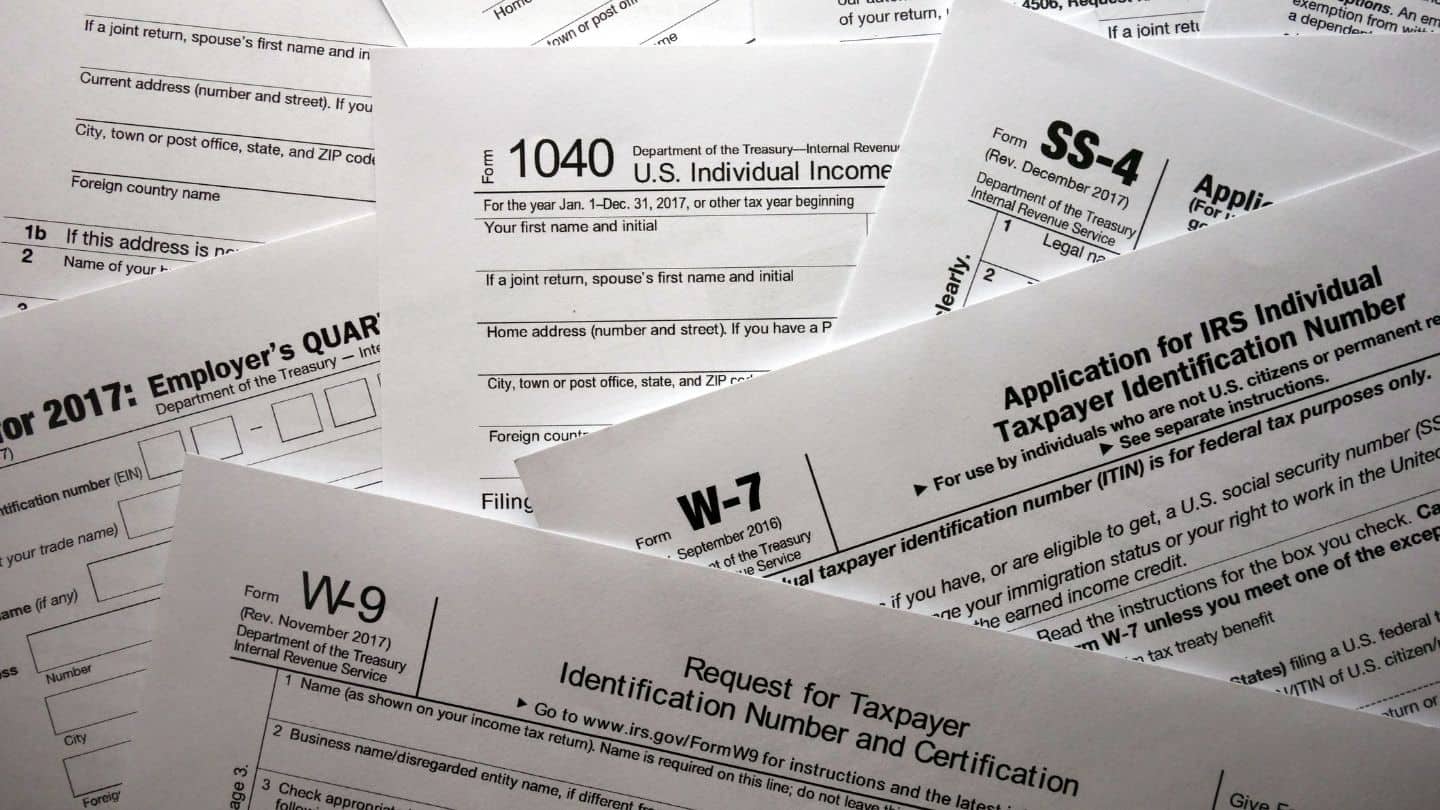
Unearned income will include interest, capital gains, and dividends earned by any holdings in the child’s account(s). As the owner, this income will be reported under their Social Security number.
If you have tax concerns, you might want to talk to your tax or financial advisor who understands your financial situation. Especially if you expect your child’s unearned income to surpass the threshold. There are other circumstances, such as if the child is a full-time student, as a parent you may be able to claim the income on your tax return. But this could also result in a higher tax burden.
Although this might seem a little daunting on your first read-through, look at it this way: if there is enough unearned income in your child’s accounts to impact taxes, yours or theirs, there is unearned income in your child’s investment accounts!! They are performing as they were intended, to make money for the future. Those initial steps you took on your child’s behalf by investing time, money, and research for their financial success are paying off!
UGMA, UTMA and Financial Aid
One final thought: Since UTMA and UGMA assets are owned by the child, they are currently counted against financial aid. The reality is that these custodial bank and brokerage accounts can reduce FAFSA-based financial aid significantly in most cases, as the assets will be expected to contribute approximately 20% towards funding the students’ college expenses every year.
The current trend is to roll UGMA or UTMA account assets into a custodial 529 college plan, which will reduce the impact of 20% on financial aid to about 6%.
How Much Can Families Save With These Methods?
- $7,500 a year in a custodial Roth IRA, tax-free for decades
- $20,000 a year in a 529 for K-12 expenses alone
- $1,350 in yearly UTMA earnings before any tax applies
- Up to $35,000 lifetime rolled from a 529 into a Roth IRA
- Roughly 14% less financial aid impact by moving UTMA funds into a 529
Those numbers only tell half the story, though. The other half is what a family does with the money they aren’t sending into an account. We wrote up the honest version of how our own family balanced paying down debt with still getting away as a family in Paying Off Debt: The Debt Snowball vs. Debt Avalanche Method, and we’ll be sharing the full numbers behind our own debt-free journey in an upcoming post. If you want a hand actually tracking where the money goes each month, our YNAB review for families walks through how we use it alongside these accounts.
Bottom Line: What’s The Best Way To Save For My Child’s Future? The Wonderful And Not So Wonderful Answer:
“Not” so wonderful first? There are so many financial instruments available to you and your child to plan for their future that it’s easy to start to become overwhelmed. When you first start researching beyond the few I touched on here, you could feel the more you know, the more you don’t. The only “don’t” you need to worry about is don’t stop yourself from taking the first step!
The wonderful part: EVERY investor or parent took that same first step at some point because no one started as an expert, NO ONE! Which means – you aren’t alone! We all have to start somewhere.
Frequently Asked Questions to Save for a Child’s Future
1. How do families afford to travel so much?
Most families who travel often treat their travel fund like a recurring bill instead of leftover cash. They automate a fixed amount into a separate account every month, stay flexible on dates and destinations, and chase deals rather than paying full price. Consistency matters more than income level here.
2. What is the 50/30/20 rule?
The 50/30/20 rule splits take-home income into three buckets: 50% for needs like housing and groceries, 30% for wants, and 20% for savings or debt payoff. Many families pull their travel fund from the 30% or 20% portion, depending on whether they’re also paying down debt.
3. What are the best apps for family budgeting?
YNAB (You Need A Budget) is a strong pick for families, running about $49 a year with one subscription shared across up to six people using zero-based budgeting. Monarch Money suits households that want unlimited collaborators on one shared budget, and Goodbudget works well for envelope-style visual budgeters.
4. How much should a family save monthly?
There’s no universal number, since it depends on income, debt, and goals. A common starting point is setting aside 5 to 10% of monthly income specifically toward savings, separate from an emergency fund. Even a small, consistent monthly amount compounds faster than waiting for extra cash to show up.
How Much Should You Save for a Child’s Future?
This isn’t a straightforward answer. The savings options available to you as parents on behalf of your family will change and grow just as your child will. It’s a process to start together. And as your child ages, it is a wonderful tool to help your child start to understand the power of interest and instituting good saving practices. It will also teach them a healthy respect for their money. And hopefully, keep them from ever having to worry about paying off debt.
Lastly, while there are so many college savings or retirement options out there, there are just as many great financial institutions available to help you with this type of planning, and many offer several no-fee accounts.
If you take anything away from this article, let it be this, although some children do run before they walk, it’s always that first step that your child took towards you that we look back on with fondness and joy…once you take those first steps to help secure your child’s financial future and college opportunities, you’ll feel confident that you are providing one of the most priceless gifts… financial security.
Book Your Trip: Logistical Tips and Tricks
Book Your Flight
Find the best flight deals with Skyscanner. It searches airlines and travel sites around the world so you can compare routes, schedules, and prices in one place.
Book Your Accommodation
Book family-friendly hotels, apartments, resorts, and vacation rentals with Booking.com. It’s an easy way to compare accommodations and find the right fit for your family and budget.
Don’t Forget Travel Insurance
Travel insurance can help protect your trip in case of unexpected delays, cancellations, lost luggage, or medical emergencies. Before your next international trip, check Nomad Insurance for coverage options.
Want to Travel for Free?
Travel credit cards can help you earn points and miles that can be redeemed for flights, hotels, and other travel expenses. Check out my recommended travel credit card resources to start making your travel budget go further.
Need a Rental Car?
Use Discover Cars to compare rental car options and find competitive rates worldwide. It’s a simple way to compare prices and find the best option for your trip.
Need Help Finding Activities for Your Trip?
Viator makes it easy to discover tours, attractions, day trips, and local experiences. Whether you’re looking for family-friendly activities or unique adventures, you’ll find plenty of options to enhance your trip.
Shopping for Travel Essentials?
From packing organizers and travel gear to family travel must-haves, you can find many of my favorite travel essentials on Amazon.
Ready to Book Your Trip?
If you’d like extra support planning your next adventure, explore curated travel experiences through Rooted Journeys, where we help families discover meaningful and memorable travel experiences around the world.